MBDA Doubles Missile Output 2023-2025; 40% Further Increase Planned for 2026
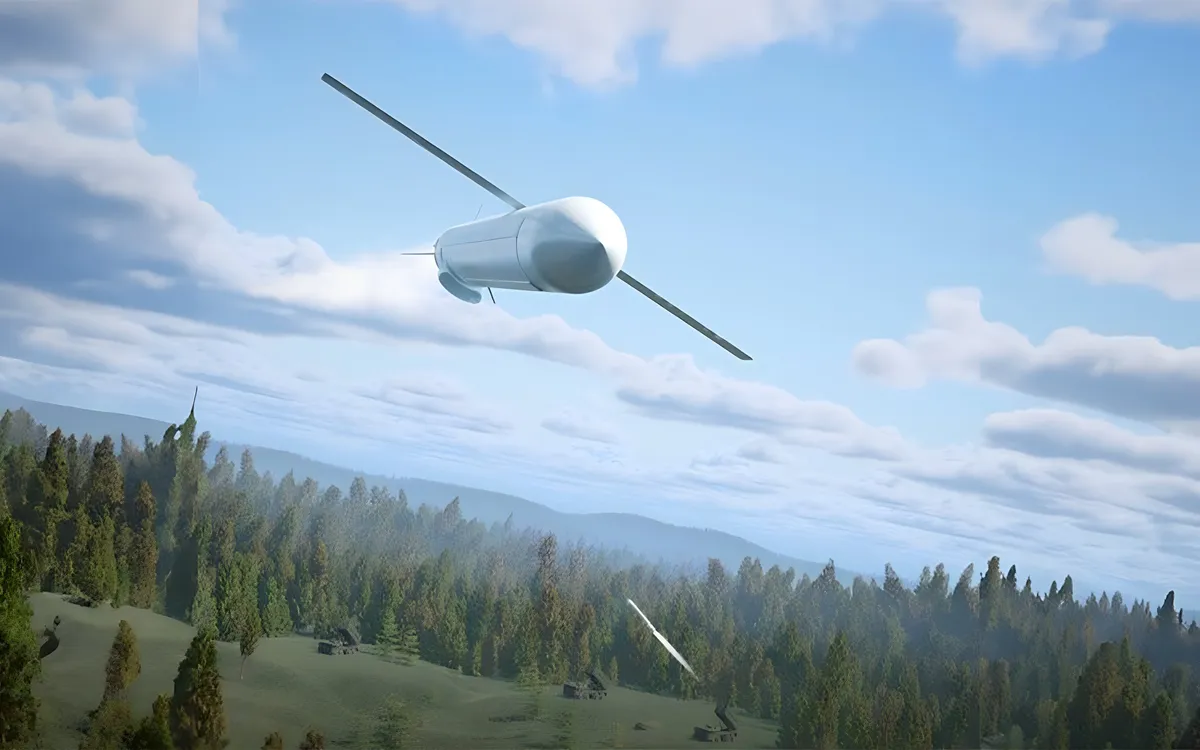
MBDA's production acceleration directly supports NATO air defense replenishment following Ukraine consumption (2022-2025) and current Middle East conflict demand. If the 40% 2026 increase is contract-backed by NATO members, it signals allied procurement planning assumes sustained high-intensity operations — either prolonged Middle East conflict or preparation for Taiwan contingency.
Conversely, if the increase is speculative capacity, MBDA is betting on geopolitical demand persistence without firm orders, a risk if the Iran-Israel cycle stabilizes or Trump's April 6 negotiation deadline produces a ceasefire.
MBDA's production ramp occurs in the active Iran-Israel-US conflict now in its fourth day of reciprocal strikes (March 24-28, 2026), where air defense and offensive missile consumption is accelerating across the region.
European missile inventory depletion during Ukraine support (2022-2025) created a supply gap that MBDA is now positioned to fill for NATO and allied customers. The timing and scale matter: a 40% increase in 2026 production suggests MBDA expects sustained demand beyond the current Middle East cycle.
However, the article provides no breakdown by missile type (air defense vs. cruise vs. anti-ship), customer nation, or contract awards — critical data for assessing whether this is demand-pull from NATO stocks or speculative capacity investment.
The article does not specify: (1) which missile systems are driving the output increase; (2) which customers or regions are the primary demand source; (3) whether the 40% 2026 increase is already contracted or speculative; (4) production bottlenecks (materials, labor, facility constraints) or how MB...
Fault Lines
Strategic intelligence, synthesized daily — with a public track record. Every call graded against what actually happened.