UK Awards £45M to Three Firms for Low-Cost Brakestop Effector Development for Ukraine
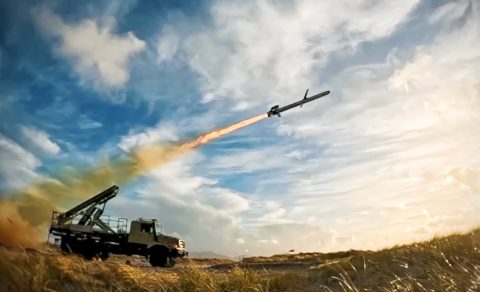
The Brakestop funding follows a clear UK industrial logic: if one contractor's design fails qualification, the other two provide insurance against a production gap. This hedging strategy costs more upfront but de-risks the Ukraine supply commitment—critical because the UK has already signaled it will not depend on US munitions approvals for future Ukraine aid.
If all three designs reach production, the UK faces a capacity-allocation decision by late 2026: which contractor gets the initial production contract, and do the others pivot to export markets (Poland, Baltic states) or stand down? The answer will shape European munitions industrial capacity for the next 3-5 years.
This extends the UK's strategy of accelerating domestic munitions production outside US supply chains—a pattern already evident in the June 21 cruise missile decoupling and June 22 long-range strike system acceleration.
The Brakestop funding locks three contractors into a parallel development track, meaning the UK is betting on multiple effector designs reaching Ukraine simultaneously rather than waiting for a single winner. The timeline matters: £45M in phase-2 funding suggests production deliveries within 12-18 months, which would overlap with the Ukraine ammunition surge already underway.
Watch the FY27 UK defence budget markup (expected September 2026) for whether Brakestop gets production-line funding or remains in development-only status.
Which three companies received the awards, and what are the unit-cost targets for each design? The article names only MBDA as a contender but does not identify the other two contractors or their cost baselines.
Fault Lines
Strategic intelligence, synthesized daily — with a public track record. Every call graded against what actually happened.