BAE Systems Completes LRASM Lot 8 RF Sensor Delivery to Lockheed; Production Scales in 2026
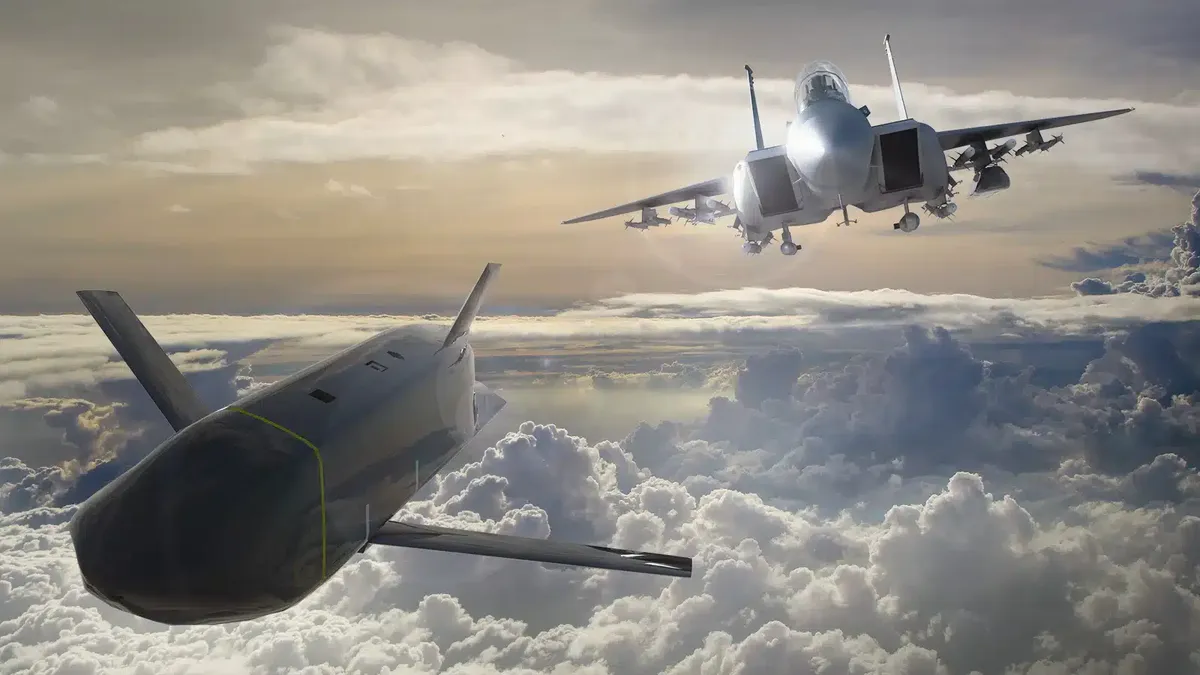
If LRASM production scales significantly in 2026 as stated, Lockheed Martin's Lot 9 and beyond will test whether the four BAE Systems sensor sites can sustain higher throughput without the same lead-time investment that Lot 8 required.
The software upgrade delivered without hardware changes is the more durable efficiency gain: if BAE Systems can push capability improvements digitally across fielded missiles, the DoD avoids a costly retrofit cycle and Lockheed Martin's integration line stays on schedule rather than absorbing hardware-change engineering orders.
Lot 8 completion against an accelerated schedule matters because LRASM is the U.S. military's primary long-range anti-ship strike weapon, and the Hormuz campaign has been consuming maritime strike inventory at a pace that was not in the pre-conflict FYDP.
BAE Systems invested in expanded electronic warfare facilities across four sites — Austin, Greenlawn, Nashua, and Wayne — specifically to absorb the production ramp, which means the sensor supply chain is not the bottleneck holding back Lockheed Martin's missile deliveries. The contract runs through 2028, so the next inflection is whether the DoD exercises options to pull deliveries forward into 2027.
What is the Lot 8 unit count, and how does it compare to the Lot 7 quantity — has the per-lot volume actually increased, or is 'accelerated' a schedule improvement on the same unit count?
Fault Lines
Strategic intelligence, synthesized daily — with a public track record. Every call graded against what actually happened.