Sweden Selects Naval Group FDI Frigate; Locks in Fifth NATO Ally to French Combat System
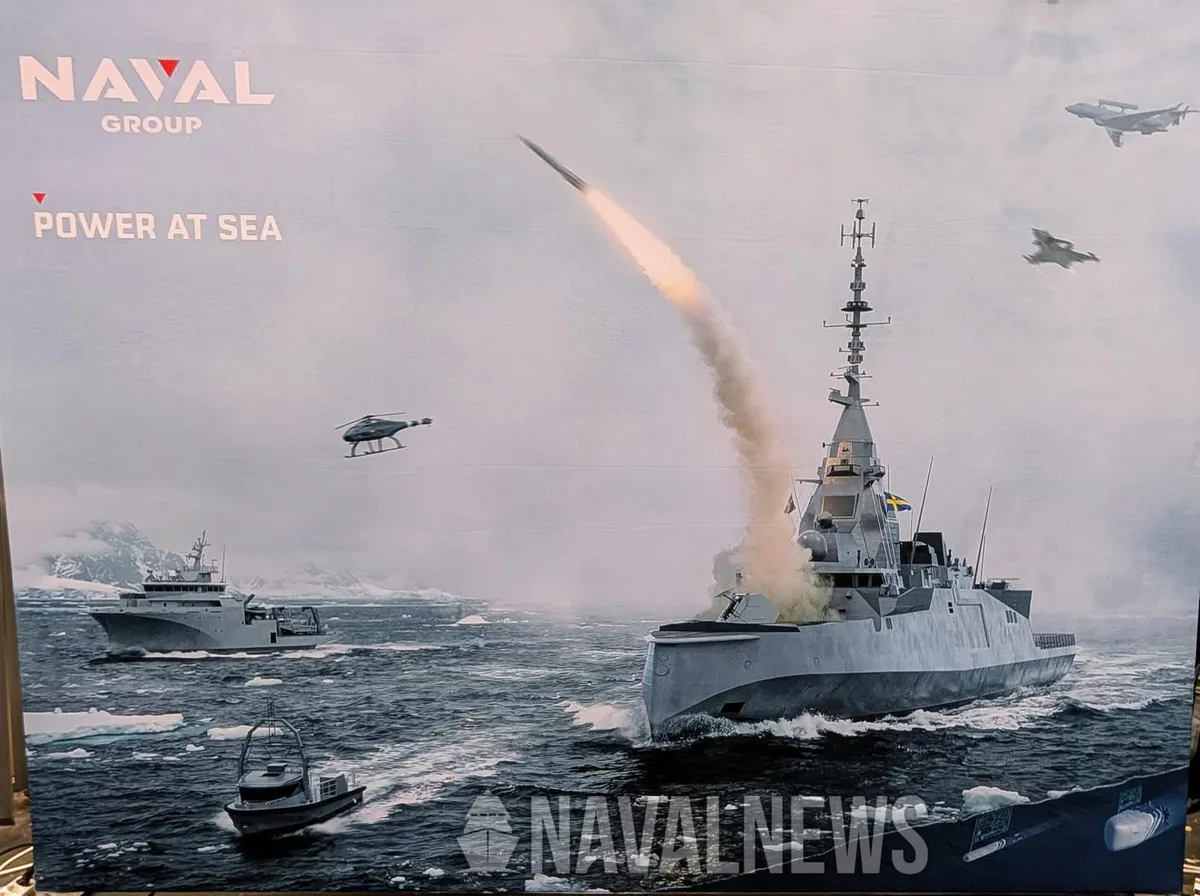
France has now locked in five NATO frigate commitments (Germany's JSM order announced same day suggests a broader European combat-system coalition forming around French platforms). If Belgium, Poland, or the Netherlands follow, French naval industrial capacity becomes the binding constraint on European frigate production through the 2030s.
This creates a structural advantage for DCNS/Naval Group in European naval modernization and subordinates Scandinavian/Baltic shipyards to French design authority — a shift from the transatlantic procurement model that dominated the 2010s.
Sweden's choice also signals confidence in the FDI's ability to integrate with NATO air-defense networks (IADS) without requiring US certification, which reduces US leverage over European frigate architecture.
Sweden's choice of the FDI over indigenous or allied alternatives signals that Scandinavia is consolidating around French naval standards rather than splitting procurement across US, UK, or German platforms — a bet on interoperability within a European pillar that excludes the US-UK AUKUS axis.
Kristersson's framing of the frigate as 'tripling Swedish air defenses' suggests the platform carries integrated air-defense responsibilities that will shape Nordic layered defense architecture. The timing, amid Russian activity in the Baltic and Swedish NATO accession consolidation, commits Swedish shipbuilding and sustainment to a 20-30 year French industrial partnership.
Watch whether Germany's JSM selection (announced same day, per recent signals) creates redundant or complementary air-defense ecosystems between Berlin and Stockholm.
What is the actual unit cost per FDI hull for Sweden, and does it include technology transfer or licensed production at Swedish yards (Karlskronavarvet, Dockstavarvet)? The article does not specify whether Sweden is buying French-built hulls or co-producing domestically.
Fault Lines
Strategic intelligence, synthesized daily — with a public track record. Every call graded against what actually happened.