EXIM Bank Funds $2.9B Stibnite Gold-Antimony Mine in Idaho; Strategic Mineral Push Accelerates
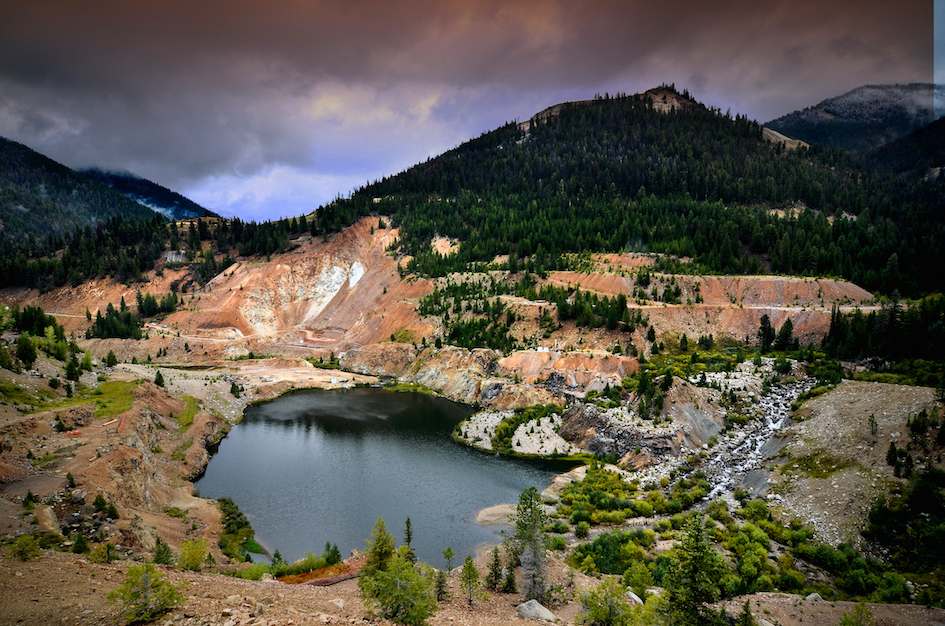
The EXIM loan is a proxy for industrial policy reorientation. If Stibnite reaches nameplate capacity and EXIM's concessional terms ($2.9B at below-market rates) become the model for other critical mineral projects, the U.S. is shifting from tariff-based supply security (Trump's stated preference) to direct capital deployment in domestic extraction and processing.
This competes with AUKUS allied procurement — if U.S. capital is locked into Stibnite, it's not available for allied critical mineral co-investment in Australia or Canada.
Watch whether Perpetua's loan triggers similar EXIM deployments for lithium (Thacker Pass, Nevada) or rare earths (Mountain Pass, California) — the aggregate tells you whether this is one-off opportunism or systematic critical mineral industrial policy.
This is a direct capital deployment to secure domestic antimony supply — a critical mineral where the U.S. has zero domestic production and China controls 70% of global output.
The EXIM loan signals that antimony supply risk has moved from a procurement issue to a national security priority warranting concessional public financing. Perpetua's timeline matters: if Stibnite reaches commercial production by 2028-2029, it reduces U.S. dependence on Chinese antimony for semiconductor manufacturing, advanced alloys, and military-grade ordnance.
Watch the project's permitting schedule and whether additional federal subsidies (CHIPS Act, Defense Production Act) flow to Stibnite or competing domestic rare earth/critical mineral projects by Q4 2026.
What is the actual production ramp timeline and nameplate capacity — and does Stibnite's antimony output target the 15,000 metric tons annually needed to supply U.S. electronics and defense manufacturing, or is this a smaller-scale hedge against supply disruption?
Fault Lines
Strategic intelligence, synthesized daily — with a public track record. Every call graded against what actually happened.